While ticketing incidents between two parties located in different countries may seem rather straightforward, some companies in the UAE assume that because the actual event was held overseas, it does not incur VAT in the UAE. Unfortunately, this is a common, and very expensive mistake that occurs frequently when the FTA (Federal Tax Authority) performs an audit.
The purpose of this blog is to illustrate the normal ticketing structure between a company in the UAE, and one in the UK, for football matches and subsequently clarifying where Vat obligations arise in UAE, based on the guidelines used by the FTA.
1. The Business Scenario
In this example, we are going to use a simple example of the normal football ticketing structure for a company in the UAE:
- The business in the UAE purchases and sells football tickets in the UK, with the football matches being played in the UK.
- The company collects proceeds from ticket sales which are directly deposited to a bank account located in the UAE.
- There is also a UK business that is involved with the actual sourcing, selling, or providing tickets to the UAE business.
2. The First Key Question is the ‘What’ part of this Supplier-branded Project
Is a company based in the UAE subject to UAE VAT?
The question is therefore: Is it VAT and how much?
Since the matches are held in the UK:
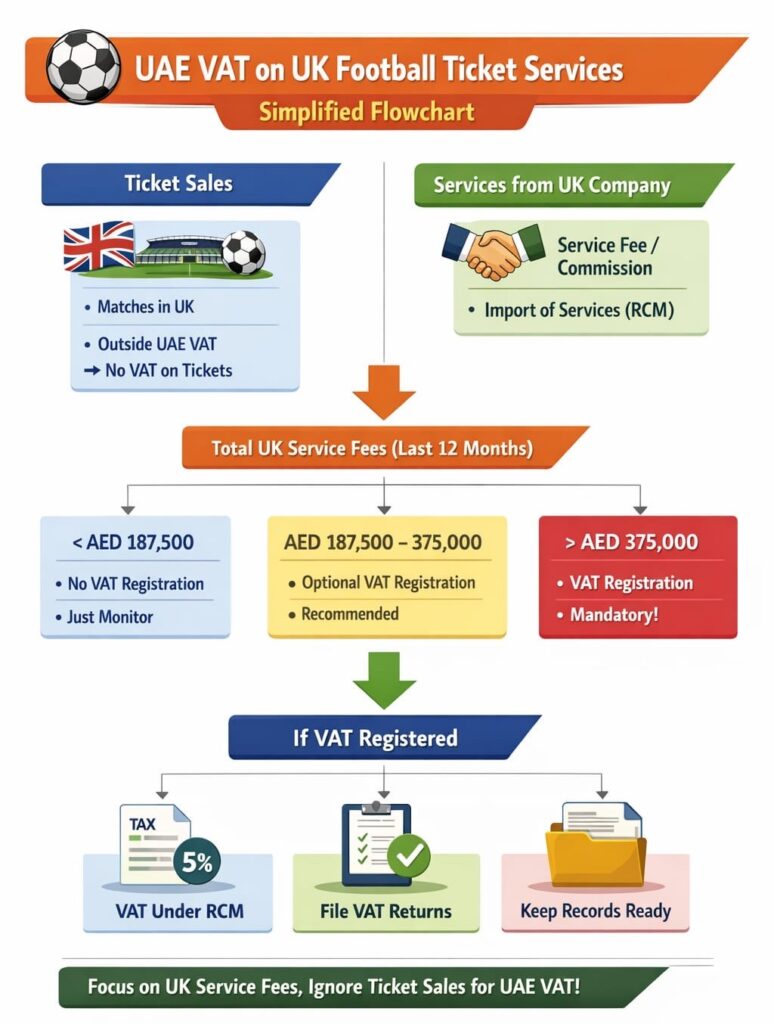
- Ticket sales are outside the scope of UAE VAT
- No UAE output VAT is charged on ticket sales
- Ticket sales do not count toward UAE VAT registration thresholds
This point is generally clear and rarely disputed.
3. The Role of VAT in the UAE
The review consists of far more than the sale of the tickets. In most situations, there is also an associated service flow relating to:
- Obtaining services
- Facilitating or handling the booking
- Operational and/or commercial support
Generally, these services are supplied to the U.A.E. company by the U.K. company. Each supply must be evaluated independently pursuant to UAE VAT laws, and larger portions of the error occur when businesses fail to account for the service leg of the structure.
4. How to Account for Services Supplied by the U.K. Company?
If:
- The supplier of the services is outside the UAE (UK company)
- The recipient of the services is an established UAE business
- Then, the B2B rule applies to establish a place of supply
The result is as follows:
- The services are now treated as being supplied in the UAE.
- The services will be treated as an import of services.
- UAE VAT will apply to imported services under the reverse charge mechanism.
It is important to understand that the true trigger for UAE VAT in this structure is the imported service, not the ticket sale.
5. Should the UAE Company Be Registered For VAT?
Registration for VAT is determined by the value of imported services, not the values of ticket sales. For purposes of determining if a company needs to register for VAT:
- Solely disregard ticket sales (they are not within scope), and
- Count imported services imported under the reverse charge mechanism.
Thresholds
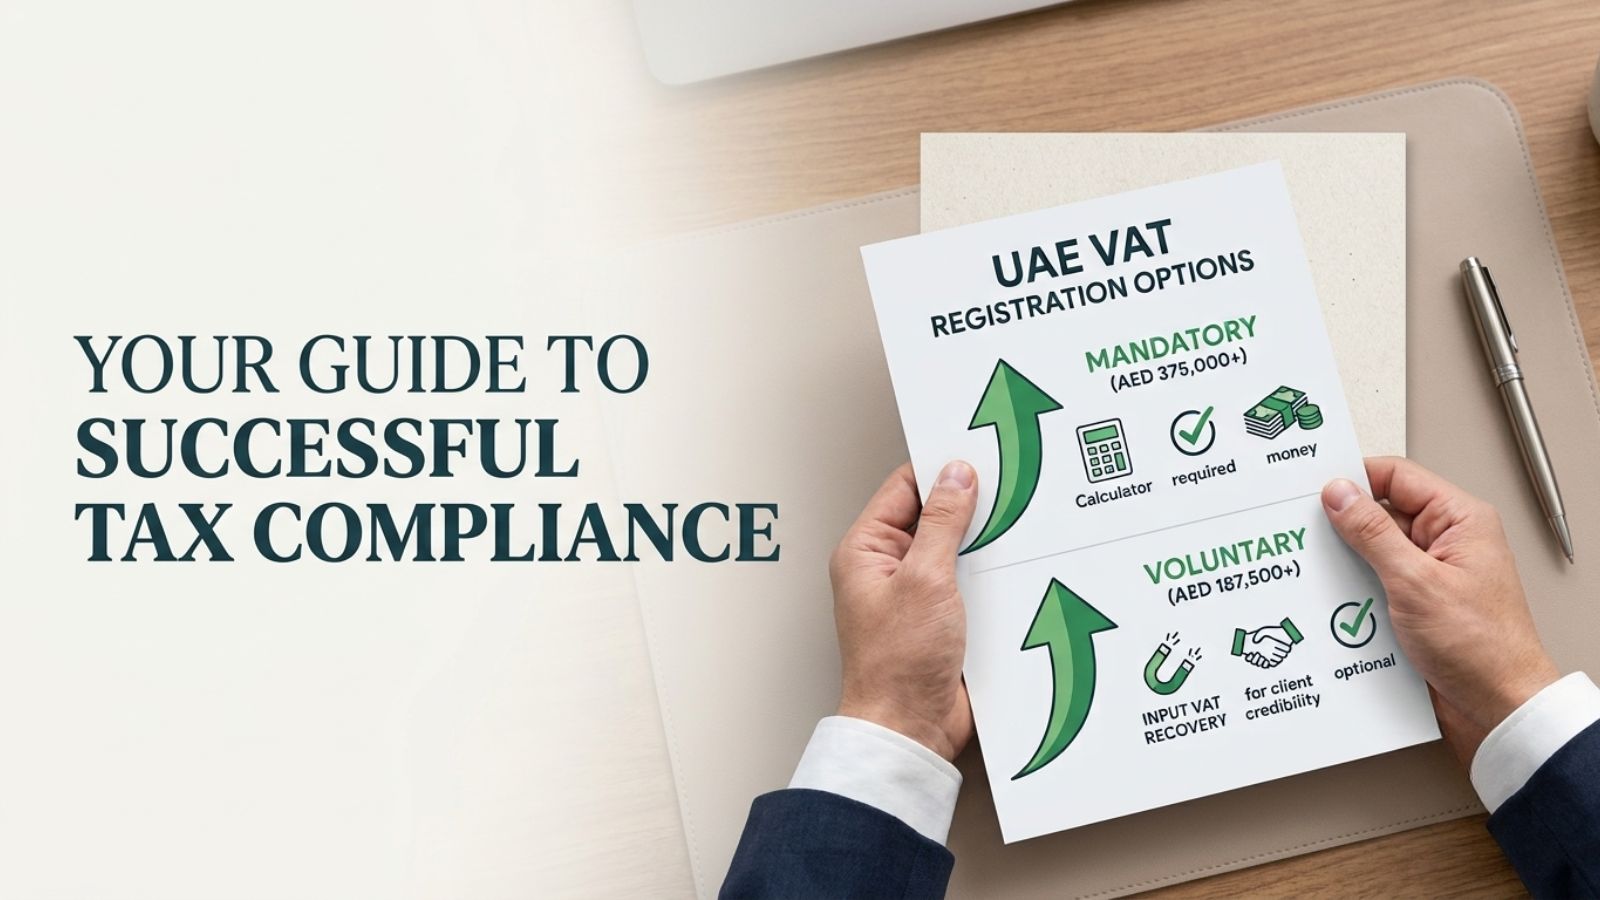
- Above AED 375,000 (rolling 12 months): VAT registration is mandatory
- Between AED 187,500 and AED 375,000: Voluntary registration may be considered
Many UAE entities fall into registration obligations without realizing it, purely due to recurring imported services.
6. RCM VAT Reclamation Process
The process of reclaiming VAT paid under the reverse charge mechanism (RCM) is not automatic. It is only possible to claim back VAT paid under RCM if:
- The imported services are used to create taxable supply in the UAE
- The supply is created outside of the UAE and would normally be considered as taxable supply if made within the UAE.
On paper, it appears possible to reclaim VAT on the supply of admission tickets, as it is not an exempt activity, but in practice the situation becomes complicated when taken into account with the FTC/FTA theory.
7. What is the FTA’s Position Regarding These Cases?
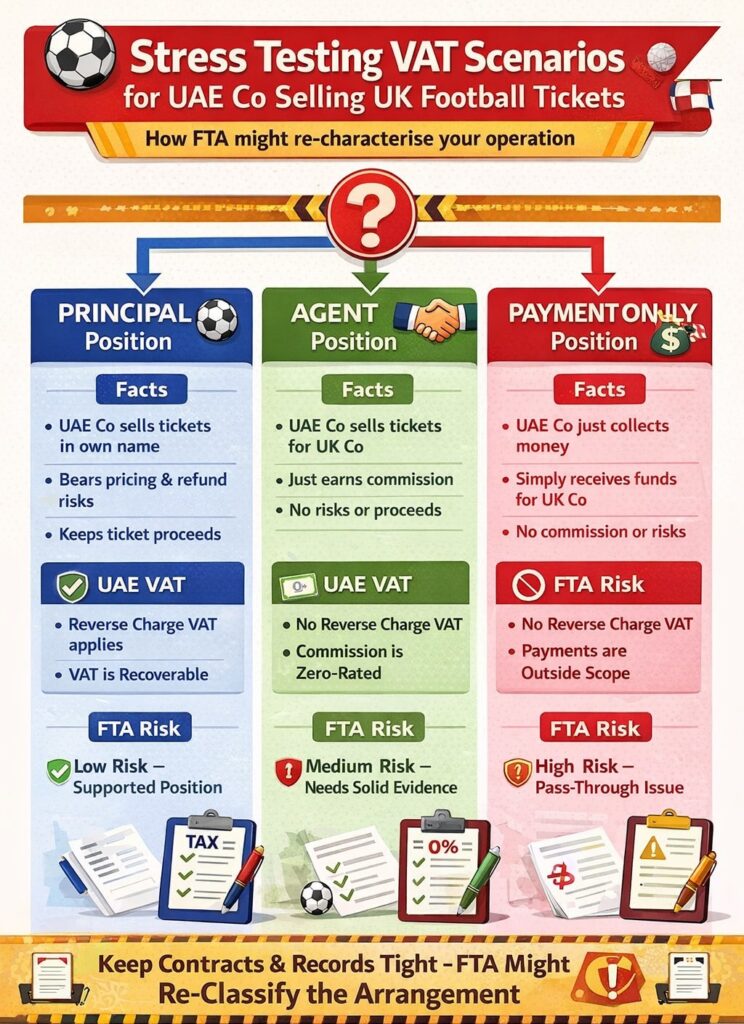
The FTA does not simply rely on labels, flow diagrams and banking flows to establish the position; it applies a commercial substance stress test to establish the answer. The key question becomes “what is an UAE company in substance?”.
8. The Three Possible Characters of a UAE Company According to the FTA
Principal of the UAE Company
Indicators of this position:
• Tickets are sold in the UAE Company’s own name;
• Price is controlled by the UAE Company;
• Risk of refunds and inventory rests with the UAE Company;
• Proceeds from the sale of tickets remain with the UAE Company;
Outcome for VAT: Reverse charge mechanism will apply to services provided by the UK, therefore there will generally be support from the VAT for recovery; it may also be necessary for the UAE Company to register for VAT if the threshold limit has been exceeded;
Comments: This is the strongest and most demanding position regarding the contract, risk allocation, and actual conduct must be closely aligned.
UAE Company as Agent
Indicators
- Sells tickets on behalf of the UK company
- Earns only a commission
- UK company bears commercial risk
VAT Outcome
- UAE company supplies agency services
- Commission typically zero-rated as export of services
- No RCM on UK services
Comment: Often the most VAT-efficient structure but only if contracts and operations are impeccably clean.
UAE Company as Payment Collector
Indicators
- Merely receives funds
- No pricing power
- No commercial risk
- No commission entitlement
VAT Outcome
- No taxable supplies
- No VAT registration required
- Input VAT not recoverable
Comment: This is the highest audit-risk scenario if facts are weak or undocumented. The FTA frequently re-characterises such arrangements.
9. The Most Common (and Costly) Error
The majority of businesses have the misconception that “All ticket sales fall outside of VAT so, therefore, the UAE company’s activities fall outside of UAE VAT.” This is incorrect. VAT supports the following:
1. Substance over form
2. Contracts over Bank Accounts
3. Risk and Control over Accounting Entries
For this reason, when you ignore the Service Leg (or Characterise this Role differently), you may incur additional assessments for your services, penalties, and you may also deny the right to recover input VAT paid.
10. Practical Takeaways
Ticket Sales are excluded from VAT Analysis if the Tickets were sold by your company, NOT a UAE Company (like your parent).
Imported Services frequently (but not always) provide a “doorway” into VAT Registration (by your Company) and recovery of VAT incurred in importing services and supplies into the UAE; but you must also consider:
- VAT Registration and recovery depend on the “true identity” of the UAE company.
- If your Company’s “Conduct” and “Documents” do not match, the FTA will change the structure of the company.
Engaging professional vat advisory in dubai is strongly recommended for businesses operating cross-border ticketing models to ensure defensibility during audits.
Conclusion
In the case of cross-border ticketing structures, VAT risk does not arise from where the match is played, but rather from the business structure and operations. How you are positioned on principal versus agent versus payment collector on paper and in actual practice will determine how defensible the business structure will be under an FTA audit.